Quick Answer: Verify which agency sent the notice, then confirm the FEIN or state account number matches your company name. From there, find the notice number, note the deadline, and respond in writing before that date. Most business tax notices are not audits. They are automated flags generated when something in an agency's records doesn't line up, and most can be resolved with a clear, written response.
IRS notices can feel alarming, but nearly all follow the same structure and ask one of a small set of questions. Once you know how to read one, you can quickly tell what the agency wants, how urgent it is, and whether you need outside help. The same approach applies to notices from state tax departments, unemployment insurance agencies, and local tax authorities.
Why your business got an IRS notice
Most business tax notices fall into a handful of categories. A number on a form you filed doesn't match a number the agency already has. A deposit or filing arrived late, or the deposit amount was off. Your filing frequency or deposit schedule changed. Or the agency needs one more piece of information before it can close out your account. Roughly 80% of the tax notices we see at Warp fall into one of these categories, and most resolve with a straightforward written response.
The IRS sends millions of notices a year, and state agencies send millions more. The systems behind them are largely automated. A mismatch between your quarterly Form 941 and your W2s. A 1099 with a tax ID that doesn't match IRS records. A deposit that posted three days after the due date. None of these mean you did something wrong on purpose, and none of them mean you're being audited. Treat the notice as a data problem to fix, not a crisis to manage.
Last quarter, one of our customers received a CP2100 after a contractor's LLC changed its legal name with the state but not with the IRS. We identified the mismatch, sent the corrected W9 request, and closed it out in nine days.
How to read any tax notice
Federal, state, and local notices look different, but they carry the same core information. Before reading the full letter, locate these details:
- The issuing agency. The letterhead tells you whether this is the IRS, a state department of revenue, a state unemployment or workforce agency, or a local tax authority. Each runs its own system, so a single error can generate notices from more than one.
- The notice or letter number. IRS notices use a CP or LTR code in the top right corner. State notices often use their own form numbers or letter IDs. This code is the fastest way to understand what's being asked.
- The notice date. Response deadlines are usually counted from this date, not from when you opened the envelope.
- The account identifier and tax period. Confirm the EIN or state account number belongs to your business and that the period referenced matches something you actually filed.
- The amount, if any. Check whether it's a balance due, a proposed penalty, a credit, or simply informational. Not every notice with a dollar figure is a bill.
- The action requested and the deadline. Most notices state plainly whether a response is required and by when. If no response is required, the notice will usually say so.
- The contact information. Use the phone number or address printed on the notice, not one found through a search engine.
Step 1: Confirm it's real before you do anything else
The IRS communicates almost exclusively by mail. It does not text you, email you, or call out of nowhere demanding payment. Most state agencies follow the same practice, though some also post notices to secure online portals. If what you received came by unsolicited email or text, threatens immediate arrest, or asks for payment by gift card or wire transfer, it's a scam. Verify separately through the IRS's official notice lookup or your state agency's official website.
For a real notice, confirm your business name and account number are correct, the tax period matches what you filed, and there's a notice number you can look up. If any of those look off, contact the agency directly using the information on its official website before responding, (be wary of AI-generated contact information on Google or other AI tools like Claude or ChatGPT).
Step 2: Decode the notice number
The notice number tells you exactly what the agency wants. These are the IRS notices growing companies see most often.
CP136: Your federal tax deposit schedule changed
The IRS reviews your deposit history every year and can move you between monthly and semiweekly deposit schedules based on your total tax liability. This notice tells you the new schedule. It's not a bill, and no response is required. Missing the new schedule does trigger a penalty, so update your calendar or payroll provider when it arrives.
CP2100 or CP2100A: A payee's tax ID doesn't match IRS records
If you filed 1099s and a name or tax ID number doesn't match what the Social Security Administration or IRS has on file, you'll receive this notice with a list of the mismatched payees. You must send each affected payee a "B notice" requesting a corrected W9, and if they don't respond, you may need to begin backup withholding at 24%. Businesses that ignore this notice can become liable for withholding they should have collected. Note that the 1099 reporting threshold increased from $600 to $2,000 for payments made after 2025.
972CG: Proposed penalty for late or incorrect information returns
This penalty notice can follow an unresolved CP2100, or arrive on its own if W2s or 1099s were filed late. The amount depends on how late the forms were and how many were affected. You have 45 days to respond with payment or a reasonable cause explanation.
CP162: Penalty for a late or incomplete partnership or S corp return
Common for businesses operating as an S corp that miss the March 15 filing deadline. The penalty is assessed per shareholder, per month, so it adds up quickly.
CP259: You didn't file a return the IRS expected
This shows up when the IRS has a record that you should have filed a return, often a 941, 944, or 940, and didn't. Sometimes it's a genuine miss. Sometimes an EIN mismatch caused the return to route incorrectly. Either way, you need to file the missing return or explain why one wasn't due.
941 penalty notices (CP210, CP220, and related)
941 notices are also common, as they reflect the payments made and applied for the quarter. When a payment lands on the wrong date, the IRS will often apply it to the wrong quarter, making it look like a balance is due. The simple fix is to call the IRS, locate the payment, and have it applied to the correct period. This is a normal IRS occurrence and should not result in penalties or interest, although the call can take hours.
State notices
State agencies issue their own versions of many of these notices, including rate notices for unemployment insurance, withholding mismatches, missing return notices, and penalty assessments. The numbering differs by state, but the same reading approach applies: identify the agency, the account, the period, the amount, and the deadline. Most state revenue and workforce agencies publish guides to their notice types on their websites.
Step 3: Put the deadline on the calendar immediately
Most IRS notices allow 30 to 45 days to respond, but state deadlines can be shorter. Some balances continue accruing interest from the original due date regardless of when you respond. The most common mistake is letting a notice sit while everyone assumes someone else is handling it. Record the deadline the day the notice is opened, and add it to the same calendar you use for payroll tax deadlines.
Federal tax deposit penalties escalate quickly: 2% for deposits one to five days late, 5% for six to fifteen days, and 10% for deposits more than fifteen days late or paid directly to the IRS instead of through EFTPS. If the amount remains unpaid more than ten days after the first IRS notice, the penalty rises to 15%.
Step 4: Decide whether to handle it yourself or bring in help
Some notices are simple, like a CP136 that requires no response or a CP2100 that requires one corrected W9. Others warrant professional support, such as a penalty you want to dispute, a notice referencing a return you can't locate, or anything involving a levy.
If you already work with an accountant, payroll provider, or tax attorney, this is exactly what they're for. To let someone talk to the IRS on your behalf, you'll need to file either Form 8821 (Tax Information Authorization, which lets someone view your records and receive copies of notices) or Form 2848 (Power of Attorney, which lets them respond and negotiate for you). Payroll providers typically use Form 8655 (Reporting Agent Authorization), which lets them file returns, make deposits, and receive copies of notices on your behalf. Payroll providers like Warp that handle compliance will have you sign one during onboarding so they can resolve notices without looping you in every time.
Step 5: Respond in writing and keep records
Phone calls can take hours and don't create a paper trail. Respond in writing, reference the notice number, account number, and tax period at the top of your letter, and send anything involving penalties or disputes by certified mail. Keep copies of everything, including the envelope, for at least four years.
If the notice requires payment, IRS Direct Pay online is the easiest option. Select the notice as your reason for payment and apply it to the tax period shown on the notice. If you're disputing the notice, say so in the first sentence and state exactly what you're disputing and why.
What happens if you ignore an IRS notice
The notice doesn't go away, and the next one is usually more serious. An unanswered CP2100 can lead to mandatory backup withholding. An unanswered 972CG becomes a final penalty with no further window to argue reasonable cause. An unanswered CP259 can lead the IRS to prepare a substitute return using assumptions that rarely favor the business.
Unpaid balances follow a predictable path. A balance due notice such as a CP161 comes first, followed by a CP504B warning that the IRS intends to levy. A final notice such as Letter 1058 or LT11 then gives you 30 days to pay, set up a payment arrangement, or request a Collection Due Process hearing before the IRS can seize funds from your bank account or receivables. The IRS can also file a federal tax lien, which becomes public record and can affect your ability to secure financing.
Payroll taxes carry an additional risk. Withheld income tax and the employee share of Social Security and Medicare are considered trust fund taxes, and if they go unpaid, the IRS can assess the Trust Fund Recovery Penalty against the individuals responsible for paying them. That means founders and officers can become personally liable for the unpaid amount. In fact, 20% of the civil penalties issued to corporations in fiscal year 2025 were due to payroll compliance issues, with more than 1.2 million penalties issued.
State agencies have similar powers, including bank levies, liens, and in some states the ability to suspend a business registration. None of this requires the agency to talk to you first, and silence is the one response that guarantees the worst version of every scenario above.
Can you get the penalty removed?
Often, yes. There are two common paths:
- First Time Penalty Abatement waives certain IRS penalties, including late filing and late deposit penalties, if your business has a clean compliance history for the prior three years and is current on its filings. It's based on your record, not an explanation, but it isn't automatic. You must request it.
- Reasonable cause applies when circumstances outside normal business operations caused the issue, such as a serious illness, a natural disaster, reliance on incorrect written advice from the IRS, or a documented system failure. General busyness does not qualify. State the request clearly in your response and include supporting documentation. Many states offer similar penalty waiver processes.
How Warp helps with IRS notices
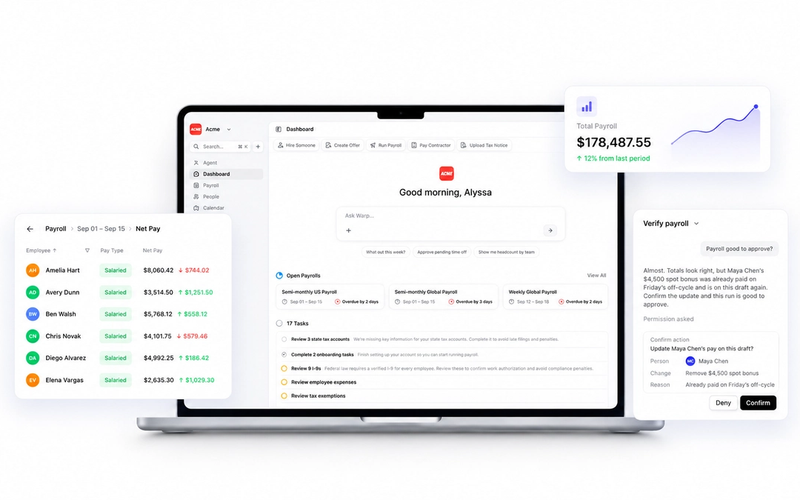
Thousands of fast growing companies trust Warp to stay compliant while they scale. Warp registers your business for payroll taxes in every state where you have employees, files and pays your federal, state, and local payroll taxes, and manages the notices that follow. You can upload any notice you receive by mail, and our tax operations team reviews it, identifies what the agency is asking for, and works directly with the agency to resolve it.
When a notice involves a penalty, our team evaluates whether there's a basis for a waiver and submits the request on your behalf. When we need something from you, such as a signed authorization or a document to complete a registration, we tell you exactly what's needed and why. Most notices are resolved with no action required on your end.
With Warp, you'll never visit a government website, negotiate with tax agencies, or pay accountants $150 per filing. Focus on building your business while Warp handles payroll, compliance, and benefits for your team across any state or country.
FAQ
Do I need a lawyer to respond to an IRS notice?
Not for most notices. Mismatches, deposit schedule changes, and first time penalty situations can usually be resolved with a written response referencing the notice number. Consider a tax attorney if a notice involves a levy, a criminal referral, or a dispute you plan to take to Tax Court.
How long do I have to respond to a tax notice?
It varies by agency and notice type. IRS notices typically allow 30 to 45 days, while some state and account-related notices allow as few as 10. Always go by the date printed on your specific notice.
What if I can't pay the amount owed?
The IRS and most states offer payment plans for businesses that can't pay in full right away. Respond by the deadline regardless and request a payment arrangement. Ignoring the notice removes your ability to negotiate terms.
Can a notice mean I'm being audited?
Rarely. Most business notices are automated mismatches or penalty assessments. An audit notice will say so explicitly and typically requests documentation for an examination rather than a payment or correction.
What's the difference between a CP2100 and a 972CG?
A CP2100 flags a mismatched name or tax ID on a 1099 and asks you to correct it with the payee. A 972CG is the penalty notice that can follow if the mismatch, or a late or incorrect filing, isn't resolved.
Do states send their own versions of these notices?
Yes. States run systems separate from the IRS, so a single underlying error can produce both a federal and a state notice. Businesses with employees in multiple states should expect notices from each state where they're registered.
This guide covers common tax notices for US-based businesses and isn't a substitute for advice from a licensed tax professional on your specific situation.